

Tens of millions of people’s stock portfolios realized an average annual loss of more than 6% during the decade that ended in 2008.
They were following traditional advice—doing everything they were told. And, still… -6.4% per year for 10 years!
I’ll walk you through all the numbers and logic so that you can be better prepared as you plan for your long-term financial goals...
More...
Recap
Over the last several posts, we’ve been on a quest to better understand the returns you should expect from your stock market investments. We went from the 12.1% simple historical average of the S&P 500 to the 10.2% geometric average. Then, we evaluated the true cost of advisor and fund fees—the industry averages there brought us down to a historically-based annualized 8.7% average return.
But, then in our last installment, we realized that it’s much more complicated than that. It’s very dependent upon your unique timeline...
If you’re only 5 years out from needing your funds, preparing for a more-than-10% per year loss would not be unreasonable—that’s happened multiple times in the past.
So, adjusting your custom financial plan based on your unique timeline really matters—it can be the difference between achieving the goals you’ve worked so hard for and… having to go back to work as a Walmart greeter just to make ends meet.
Unfortunately, it gets even more complicated...
The Last "But Wait There's More!"
When you’re not putting money into or pulling money out of your investment accounts, the order of returns doesn’t matter.
Put another way, if I reverse the order of every annual return since 1926 and apply it to our same $100 investment assumption that we’ve been revisiting throughout this series, we’ll still end up with the same $4.6MM (from the example in our earlier posts) 94 years later—even though the crash of 1929 would have just happened!
We would have the same simple average return of 12.1% and actual return of 10.2%.
But, how often is it the case that we’re not contributing to or pulling from our investment accounts?
Sequence Risk
Before retirement, we are (presumably, or at least would like to be) contributing to our accounts every year.
During retirement, we are likely pulling from our accounts each year.
During these stretches of regular contributions or withdrawals, the order of those returns actually makes an enormous difference. This is called Sequence of Returns Risk or just Sequence Risk.
When adding this reality into your planning considerations (as we do with our clients), you discover that historically-based, time-period-specific highs could be even higher, and the lows... could be much lower.
Meaning that -13.7% annualized return for our historically-worst-ever 5-year period, could actually be even worse for an individual investor depending on the specific sequence of returns and whether they just so happened to be contributing or withdrawing.
Before we explore the now-even-more depressing ‘worst-case’ historically-based scenario, let’s evaluate a perfectly average 10-year period, 1974-1983 (for the time being, we’ll ignore the crazy inflation of that era). The real average annual return over this period was 9.1% (compared to the average for all 10-year periods of 8.9%).

Contributions
As we explore the impact that sequence risk has on your account during periods of contributions, (just at first) let’s leave out all the fee assumptions—let’s look at the bottom-line impact that this one simple factor can have on your success.
The simple average return of these 10 years is 12.4%. If you made a $5,000 contribution at the beginning of each year (for those 10 years) into an account that’s tracking the S&P 500, it would have grown to $110,000 (excluding fees) by the end of 1983.
Bad Years First
What if we mixed up the order of those returns? What if all the worst years were first and the best years last?
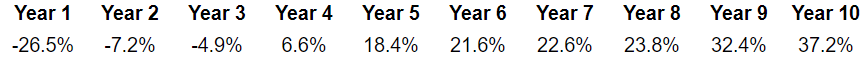
With all the other assumptions the exact same as last time, your account would now grow to $151,000. That’s $41,000—37%—more over that same 10-year period with those same returns ...just in a different order.
That’s an effective 23.09% return.
Nice!
That’s even better than the best 10-year period in the entire S&P 500’s recorded history (which was 18.4%, by the way).
How is that possible? How’d it go from a very plain vanilla ‘average’ return decade to better-than-the-best?
It’s because w